

Section 7508A(d), as in effect in 2020, provided a mandatory postponement of certain time-sensitive acts for qualified taxpayers affected by a federally declared disaster. Because the COVID-19 disaster declarations covered the entire country, every taxpayer was potentially eligible. The question that has generated a wave of Form 843 claims is simple: how long did the COVID-19 postponement period last? On that question, the IRS has given two incompatible answers.
The IRS’s Official Position: 60 Days
In Abdo v. Commissioner, 162 T.C. 148 (2024), the Tax Court held that former section 7508A(d) provided an automatic and mandatory postponement beginning January 20, 2020. The IRS did not appeal. Instead, in its Action on Decision, the IRS acquiesced “only to the Tax Court’s holding that the COVID-19 disaster declarations created a mandatory 60-day postponement period from January 20, 2020, to March 20, 2020,” and expressly declined to acquiesce in “an interpretation that would result in any further postponement beyond the 60 days provided by the Tax Court in Abdo.”[1] The IRS Independent Office of Appeals has adopted the same 60-day view.[2]
That position is consistent with the government’s litigating posture in Kwong v. United States, 179 Fed. Cl. 382 (2025), in which the Court of Federal Claims held that the mandatory relief period ran from January 20, 2020, through July 10, 2023 — 60 days after the COVID-19 emergency ended on May 11, 2023. The government has appealed that decision.
What the IRS Is Telling Taxpayers: Through July 10, 2023
The IRS’s letters to taxpayers tell a different story. In responding to Kwong claims, the IRS has repeatedly described the relief period as extending through July 10, 2023 — the very period it refused to accept in its acquiescence. A September 28, 2026, Letter 916C states that “[r]elief applies only to qualifying penalties and interest for the period Jan. 20, 2020, through Jul. 10, 2023.”[3] (See Figure 1.)
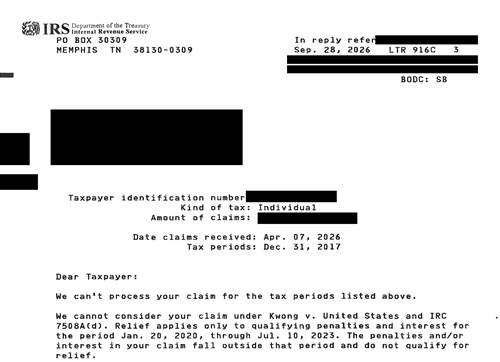
Figure 1. IRS Letter 916C (Sept. 28, 2026), tax year 2017: relief applies to “the period Jan. 20, 2020, through Jul. 10, 2023.” Identifying information redacted by the authors.
A September 2, 2026, notice of claim disallowance (Letter 105C) likewise refers to a “target timeframe of March 20, 2020, through July 10, 2023.”[4] (See Figure 2.) That letter not only adopts the July 10, 2023, end date but also uses a different start date — March 20, 2020, which is the date the IRS says the relief period ended.
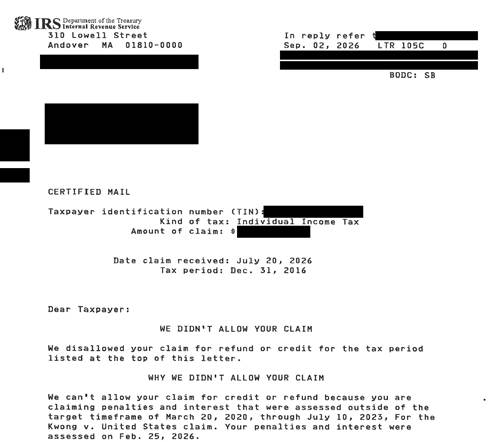
Figure 2. IRS Letter 105C (Sept. 2, 2026), tax year 2016: amounts “assessed outside of the target timeframe of March 20, 2020, through July 10, 2023.” Identifying information redacted by the authors.
The IRS Does Not Appear to Know What Its Position Is
These positions cannot be reconciled. In its acquiescence, the IRS views the COVID-19 emergency postponement period as lasting only 60 days, from January 20 to March 20, 2020. In its communications to taxpayers, the IRS says the period for relief extends through July 10, 2023. Both cannot be right, and the IRS does not appear to know what its position is.
The confusion has consequences. Taxpayers reading these letters would reasonably conclude that the IRS accepts a relief period running through July 10, 2023, and that their claims were denied only because their particular penalties or interest fell outside it. Yet the IRS’s published position rejects any relief beyond March 20, 2020. Taxpayers are entitled to know the rule the IRS is actually applying. Until the IRS says which period it recognizes — and applies that period consistently — practitioners should preserve their clients’ claims, request that claims be held pending the outcome of the Kwong appeal, and calendar refund-suit deadlines conservatively.
These letters are just a fraction of the inconsistent positions we have seen the IRS take when it comes to availability of the mandatory 7508A(d) suspension period for the COVID pandemic. In a more comprehensive article, we describe the plethora of inconsistent and contradictory responses taxpayers who are claiming this relief have received from the IRS.
[1]AOD 2026-1, 2026-23 I.R.B. 1556 (June 1, 2026).
[2]IRS Independent Office of Appeals, Memorandum AP-08-0626-0016 (2026).
[3]IRS Letter 916C to Taxpayer C (Sept. 28, 2026) (tax year 2017) (on file with authors).
[4]IRS Letter 105C to Taxpayer E (Sept. 2, 2026) (tax year 2016) (on file with authors).